Term Life Versus Disability Insurance: What Fits?
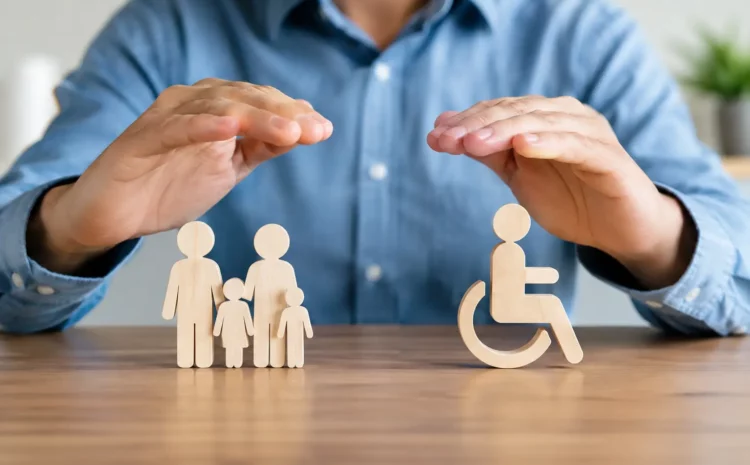
A mortgage payment still arrives when an illness or injury keeps you from working. So do groceries, childcare costs, utility bills, and loan payments. That is the practical difference at the center of term life versus disability insurance: one is designed to protect the people who depend on you after death, while the other is designed to help protect your income while you are alive.
For many working adults, this is not an either-or decision. It is a question of which risk creates the most immediate financial pressure in your household and how to build protection around it without overcomplicating the process.
What Term Life Insurance Is Built to Protect
Term life insurance pays a tax-free lump sum to your named beneficiary if you die during the policy term. You choose the coverage amount and the length of the term, often to match a period of financial responsibility such as a mortgage, young children at home, or income replacement needs.
A healthy 35-year-old parent, for example, may choose a 20-year term policy so their family has financial support until the mortgage is lower and the children are more independent. The benefit can help a surviving partner manage daily living expenses, debts, education costs, and future plans without having to make rushed financial decisions.
Term coverage is generally straightforward: if you die while the policy is in force, the insurer pays the approved death benefit. It does not replace your paycheck during an illness, and it does not pay because you cannot work. Its role is family protection after a loss of life.
When term life is often a priority
Term life insurance tends to be especially relevant when someone else would face a financial hardship if your income disappeared permanently. This may include a spouse, children, a co-signer, or business obligations that would not simply vanish at death.
It can also make sense for people with significant debt, even if they do not have children. A partner who would need to carry the rent, mortgage, or shared credit obligations alone may need more protection than they realize.
What Disability Insurance Is Built to Protect
Disability insurance can pay a monthly benefit if an illness or injury prevents you from working and you meet the policy’s definition of disability. The benefit is intended to replace part of your income, helping you stay current on the bills that continue while you recover.
That distinction matters because a disability can be temporary, long-lasting, or permanent. A serious back injury, cancer treatment, a mental health condition, or complications from an illness may prevent a person from doing their regular job even though they are alive and still supporting a household.
Policies commonly include an elimination period, which is the time you must wait before benefits begin. They also have a benefit period, which is how long benefits may continue if you remain disabled. A shorter waiting period can offer faster support, while a longer waiting period may reduce the premium if you have enough savings or employer coverage to bridge the gap.
The definition of disability deserves close attention
Not all disability policies work the same way. Some focus on whether you can perform the duties of your own occupation. Others may assess whether you can work in any occupation that is reasonably suited to your education, training, or experience.
For a surgeon, dentist, contractor, executive, or self-employed professional, that difference can be significant. A person may be able to work in some capacity but still be unable to perform the occupation that produces their usual income. This is one reason disability coverage should be reviewed beyond the monthly premium alone.
Term Life Versus Disability Insurance: The Real Choice
The simplest way to compare term life versus disability insurance is to look at the event each policy addresses. Term life protects against the financial impact of death. Disability insurance protects against the financial impact of being unable to earn an income due to a covered condition.
The likelihood of needing each type of protection is not the only factor. The size and timing of the financial impact matters, too. A long disability can put immediate pressure on a household’s cash flow. A death can create an even larger, permanent loss for surviving family members. Both risks can affect the same financial goals, but they call for different solutions.
If your budget only allows for one policy today, start with the question: what would put your household in crisis first? Someone with young children, a large mortgage, and one primary income may place an urgent priority on term life insurance. A single professional with no dependents but high fixed expenses and no paid sick leave may find disability insurance more urgent.
That said, delaying life insurance can become more expensive as you age or if your health changes. Delaying disability insurance can be equally difficult if an injury or diagnosis occurs before coverage is in place. The right approach is often to begin with the most urgent need, then add the other protection as the budget allows.
Start With Your Income, Not Just Your Debts
Many people calculate life insurance based only on their mortgage balance. Debt is part of the picture, but income is usually the larger issue. Ask how long your household would need financial support if your earnings stopped, and what expenses would remain after a disability or death.
For disability insurance, review your monthly essentials: housing, food, transportation, insurance, childcare, debt payments, and savings commitments. Then compare that figure with any coverage through your employer. Group plans can be valuable, but benefit limits, waiting periods, taxable benefits, and portability can affect how much protection they actually provide.
For term life insurance, consider outstanding debt alongside income replacement, child care, education savings, funeral costs, and a financial cushion for your family. A stay-at-home parent should not be overlooked. Replacing child care, household management, and other unpaid work can be costly.
How Coverage Can Work Together
A practical protection plan often uses both policies for different jobs. Disability insurance helps support the household while you are unable to work. Term life insurance provides a larger lump sum if you die during the period when others rely on you financially.
Consider a couple in Ontario or Quebec with a new home and a child. One partner may have strong workplace disability benefits, while the other is self-employed with limited protection. Their plan might focus first on individual disability coverage for the self-employed partner and term life coverage for both people. The exact mix depends on income, available savings, health history, workplace benefits, and family responsibilities.
There is no value in buying more insurance than your situation requires. There is also risk in assuming workplace benefits or savings will cover every gap. A clear needs assessment helps identify a coverage amount and policy design that fits the life you have now, with room to adjust as it changes.
Questions to Ask Before You Apply
Before comparing quotes, gather the details that shape a useful recommendation. Know your household income, monthly expenses, debts, existing workplace benefits, savings, and the people who rely on you. For disability coverage, be ready to discuss your occupation and how you perform your work. For life insurance, think through the financial outcome you want to create for your beneficiaries.
Also ask how long your protection needs are likely to last. A 10-year term may suit a short-term loan, while a 20- or 30-year term may better match a mortgage and the years children depend on you. With disability insurance, consider how long you could manage without a paycheck and whether returning to a modified role would still meet your financial needs.
A licensed broker can compare options from multiple insurers, explain the trade-offs in plain language, and help coordinate life and disability coverage around one plan. At GSA Financial Services, the goal is to make that process direct: understand the need, compare suitable options, and help you apply with confidence.
The best time to review income protection is while you still have choices. Start with the bills your income supports and the people your life supports, then put coverage in place that lets your household keep moving forward if work, health, or life takes an unexpected turn.